How do DSCR loans work for real estate investors?
The short answer
A DSCR loan lets real estate investors buy or refinance rental properties based on the property's rent instead of personal income or tax returns. Most programs want the rent to cover the full payment, about 20% to 25% down, and a few months of reserves. The Mortgage Advisory is the direct lender on DSCR loans in California, Texas, and Colorado (in Florida, we arrange them as a licensed mortgage broker), and we're upfront about rates and prepayment penalties.
Single-family rentals 
Duplexes 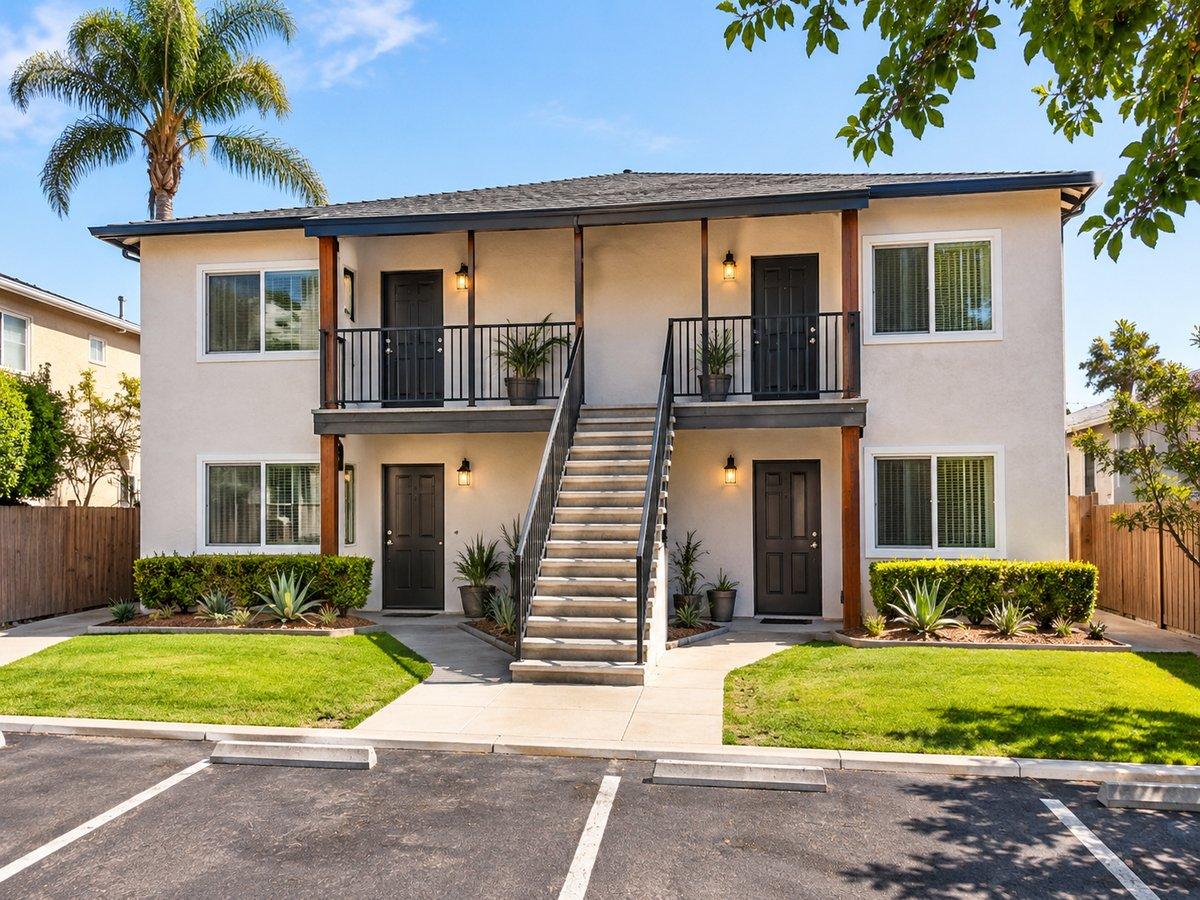
Triplexes and fourplexes
Who are DSCR loans for?
- Investors growing a rental portfolio who've outgrown conventional limits
- Self-employed investors whose tax returns don't show their real income
- Investors whose debt-to-income is maxed out from other properties
- Anyone buying in an LLC
- Out-of-state investors buying in California, Texas, Florida, or Colorado
DSCR loans are for investment properties only, not the home you live in.
How does a DSCR loan work?
We compare the property's monthly rent with its full monthly payment (principal, interest, taxes, insurance, and HOA dues). If the rent covers the payment, the property qualifies on its own. No tax returns, W-2s, or pay stubs. How to calculate DSCR →
What can I finance?
| Property | Purchase | Refinance | Cash-out |
|---|---|---|---|
| Single-family rentals | Yes | Yes | Yes |
| Duplex, triplex, fourplex | Yes | Yes | Yes |
| Condos and townhomes | Yes | Yes | Yes |
| Short-term rentals (Airbnb, VRBO) | Many programs | Many programs | Many programs |
You can close in your personal name or an LLC. DSCR loans in an LLC →
What does a DSCR loan cost?
I'll be straight with you:
- Higher rates than conventional investment loans, because DSCR loans can't be sold to Fannie Mae or Freddie Mac
- Down payment of about 20% to 25% on most purchases
- Prepayment penalties are common, often for the first one to five years. I'll show you the penalty options in dollars. How prepayment penalties work →
- Closing costs commonly 2% to 5% of the loan amount, plus any points you choose
- Reserves: usually 3 to 12 months of payments left in the bank after closing
DSCR or conventional?
If your income is easy to document and your debt-to-income has room, a conventional investment loan usually costs less. DSCR wins when your tax returns understate your income, you're near the 10-property limit, or you want an LLC. We offer both. Compare DSCR vs. conventional →
Example scenario (illustrative)
An investor in Phoenix already owns eight rentals and lives in California. She finds a duplex near Austin for $420,000 with $3,600 in total rent. With 25% down and Texas property taxes, the full payment is about $3,150, a ratio of 1.14. She closes in her LLC without showing a single tax return, and uses a DSCR cash-out refinance on an older rental to fund her next down payment.
Our take
DSCR loans are the tool that lets serious investors keep buying. The deal only works if the property truly cash-flows, so I run every ratio with real rent, real insurance quotes, and the actual property tax rate, and I show you the prepayment terms before you commit.
Who funds your loan?
We're the direct lender on this loan. We make the loan decision and fund it ourselves. (In Florida, where we're licensed as a mortgage broker, we arrange it through an approved lender and tell you upfront who your lender is and how we're paid.)
Questions people ask
- What is a DSCR loan, and how do I qualify for one?
- What are the requirements for a DSCR loan?
- How do you calculate DSCR on a rental property?
- How much down payment do I need for a DSCR loan?
- How do prepayment penalties work on DSCR loans?
- DSCR loan vs. conventional investment loan: which is better?
- Can I do a cash-out refinance on a rental with a DSCR loan?
- Can I use a DSCR loan for an Airbnb or short-term rental?
- Can I get a DSCR loan in an LLC?
- Is there a limit on how many rental properties I can finance with DSCR loans?
Ace Ausar, Mortgage Banker · NMLS #1143018
The Mortgage Advisory, Inc. · NMLS #1549739
Reviewed by Ace Ausar, NMLS #1143018 · Updated
Want to see your numbers?
Ask the AI assistant, or book a call with an advisor. No pressure, made simple.